
Spanish Tax Laws
If you live in Dubai and have income, assets, or plans in Spain, it is worth understanding how Spanish tax laws may affect you. Your tax position can change depending on residence, property ownership, and the source of your income.
In Díaz & Asociados guide, we explain the key rules clearly, so you can see where you stand and what deserves closer review.
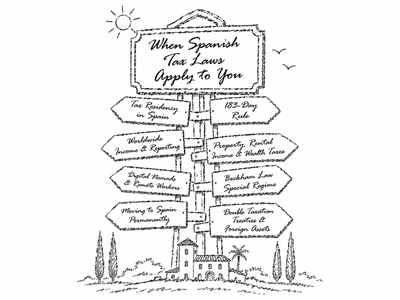
When Spanish Tax Laws Apply to You
To understand whether Spanish tax laws apply to you, we need to start with your tax residence status.
Spanish rules draw a clear line between tax residents and non-residents, and that distinction affects the scope of taxation in Spain.
Article 9 of the Personal Income Tax Law sets the main criteria, and the Spanish Tax Agency explains them in the same terms.
Personal Income Tax for residents
If you are a tax resident in Spain, your income is generally taxed under Personal Income Tax, known as IRPF.
This tax is governed by Law 35/2006 and covers worldwide income, which means Spain may look at employment income, business income, investment income, and capital gains together under the resident tax system.
Non-Resident Income Tax
If you are not a tax resident in Spain, income obtained in Spain usually falls under Non-Resident Income Tax, known as IRNR.
This includes many common situations for foreign nationals, such as Spanish rental income, certain capital gains, and other income linked to Spanish territory.
The legal framework is set out in Royal Legislative Decree 5/2004, and the Spanish Tax Agency provides specific guidance for non-residents.
Wealth Tax exposure in Spain
Spain also levies Wealth Tax under Law 19/1991.
This tax focuses on net wealth rather than annual income, so it may become relevant when you hold high-value assets in Spain or, in some cases, wider assets depending on your residence status.
For foreign nationals with significant holdings, this is often one of the first taxes worth checking.
Capital gains tax
Capital gains tax becomes relevant when you sell an asset and make a profit.
In Spain, gains on the sale of real estate are a frequent issue for foreign owners, and the Tax Agency explains that gains derived from the transfer of urban properties located in Spain fall within the applicable tax rules for non-residents.
For residents, gains are generally integrated into the IRPF system.
Rental income tax
If you earn rental income from a property located in Spain, that income is taxable in Spain.
For non-residents, the Tax Agency treats income derived from Spanish real estate as subject to Non-Resident Income Tax, and the exact treatment depends on whether the property is rented out, kept for personal use, or held by more than one owner.
Inheritance and gift tax
Inheritance and Gift Tax applies when assets or rights are received without payment, whether by inheritance or by gift. The main law is Law 29/1987, and the Spanish Tax Agency confirms that non-residents may also have filing obligations when the inheritance or donation falls within the Spanish rules.
This tax deserves separate review because residence, location of the assets, and regional rules can all affect the outcome.
Property-related taxes
Property ownership in Spain may trigger other taxes beyond income tax.
Depending on the transaction and the type of property, you may need to review Transfer Tax and Stamp Duty, VAT on certain real estate transactions, and local property taxes regulated under the Local Finance Law.
This is why property purchases, sales, and ongoing ownership should always be reviewed as separate tax events.
Spanish Tax Rules for UAE Residents
Living in Dubai or elsewhere in the UAE does not automatically place you outside Spanish tax rules. Spain may still tax certain income, assets, or property interests when there is a sufficient link with Spanish territory, and the starting point is always your residence status and the source of the income.
When a UAE resident may still have tax obligations in Spain
A UAE resident may still have tax obligations in Spain when they earn Spanish-source income, hold property in Spain, sell Spanish real estate, or meet the legal tests for Spanish tax residence.
Spanish tax law looks at residence, days of presence, and economic ties, while the non-resident rules cover income obtained in Spain even when the taxpayer lives abroad.
How Spanish-source income is taxed
When income is considered to arise in Spain, it generally falls within the Spanish tax net.
For non-residents, this usually means taxation under Non-Resident Income Tax, and the specific treatment depends on the type of income, such as rental income, capital gains, or other returns connected to Spain.
The Spanish Tax Agency explains these rules through its non-resident guidance.
Owning property in Spain while living in Dubai
If you own property in Spain while living in Dubai, Spain may tax the income generated by that property and may also impose obligations linked to ownership itself.
A rented property can create taxable rental income, while a property kept for personal use may still have tax implications under the non-resident rules.
If you later sell the property, any gain may also be taxed in Spain.
Spending part of the year in Spain
If you spend part of the year in Spain, the number of days becomes important.
Spanish law treats you as habitually resident in Spain when you remain in Spanish territory for more than 183 days during the calendar year, and it also considers where your main economic interests are based.
For internationally mobile individuals between Spain and the UAE, this point deserves careful review before filing any return.
Why the Spain and UAE tax treaty matters
The tax treaty between Spain and the United Arab Emirates matters because it helps determine which country has taxing rights over certain categories of income and offers a framework to avoid double taxation.
It also provides tie-breaker rules for residence in cases where both countries may claim a connection to the taxpayer.
For cross-border cases involving Spain and Dubai, this treaty is one of the key documents to review alongside domestic tax law.
Special Tax Regimes for Expats Moving to Spain
Spain offers a special tax regime for certain individuals who move to Spanish territory for work or qualifying economic activity. This regime is widely known as the Beckham Law, although its official legal basis is Article 93 of the Personal Income Tax Law.
The Spanish Tax Agency refers to it as the special tax regime for workers, professionals, entrepreneurs, and investors relocating to Spain
The Beckham Law
The Beckham Law allows qualifying individuals to opt for a special tax treatment after moving to Spain. Under this regime, the taxpayer remains within Personal Income Tax but applies a system largely aligned with the rules used for non-residents.
For internationally mobile professionals, this can have a significant impact on the overall tax position after arrival in Spain.
The current rules apply to workers, professionals, entrepreneurs, and investors who relocate to Spain and meet the legal conditions.
One of the main requirements is that the individual must not have been tax resident in Spain during the five tax periods before the move. The Tax Agency also sets out the formal option through Model 149.
Key tax advantages
The main attraction of this regime is that it can produce a more favourable result than the ordinary resident tax system in certain cases.
Article 93 sets a general rate of 24 percent up to 600000 euros and 47 percent on the excess for the relevant taxable base covered by the regime. This framework is often one of the first points worth reviewing for executives, founders, and highly paid professionals moving to Spain.
When this regime may be worth reviewing
This regime deserves attention when you are planning a move to Spain for employment, a new professional activity, an entrepreneurial project, or an investment-based relocation. It is also worth reviewing early, because the option follows a formal procedure and timing matters.
A proper review should look at your previous tax residence, your source of income, and the way your move to Spain is structured.
Tax Returns and Filing Obligations in Spain
When Spanish tax rules apply to you, the next step is identifying which return must be filed. The model depends on whether you are a tax resident, a non-resident, or a taxpayer with net wealth above the relevant threshold. The Spanish Tax Agency provides a separate filing route for each of these situations.
- Personal Income Tax return: if you are a tax resident in Spain, the usual return is the Personal Income Tax return. This is filed through the annual income tax campaign and covers the income taxed under IRPF. The Spanish Tax Agency handles this process through the income tax section and the related filing services.
- Non-Resident Income Tax return: if you are not a Spanish tax resident and receive income from Spain, you may need to file a Non-Resident Income Tax return. The usual form is Model 210, which the Spanish Tax Agency uses for many common non-resident situations, including Spanish property income and certain gains.
- Wealth Tax return: if Wealth Tax applies to your case, the filing is generally made through Model 714. This return is relevant for taxpayers whose net wealth falls within the scope of the Spanish Wealth Tax rules. The form and filing route are set out by the Spanish Tax Agency.
Some cases require additional reporting. This may happen when you hold assets abroad, receive specific categories of foreign income, or fall within a particular international reporting obligation. One example is Model 720, which the Spanish Tax Agency reserves for certain foreign assets and rights.
Each return follows its own filing period and formal requirements. A late or incorrect filing may lead to surcharges, interest, or penalties under the General Tax Law, so it is important to match the correct model to the correct tax position from the outset.
When You Should Speak to a Spanish Tax Lawyer
Some cross-border situations deserve legal review before you file anything or make a move. When Spain and the UAE both connect to your income, your assets, or your residence status, a clear legal review helps you understand where you stand and what you need to do next.
At Diaz & Asociados, we often support clients at this stage, with the aim of giving them clarity before tax issues grow.
Moving from Dubai to Spain
If you are relocating from Dubai to Spain, your tax position can change quickly once Spanish residence tests begin to apply.
The 183-day rule, economic interests, and family ties may all become relevant, so this is usually the right moment to review your situation with care.
Buying or selling property in Spain
A property purchase or sale in Spain can trigger several tax issues, including non-resident taxation, capital gains, and property-related obligations.
These transactions are easier to manage when the tax treatment is reviewed early and the filing route is clear from the start.
Receiving rental income from Spain
If you receive rental income from Spanish property while living in the UAE, that income is generally taxable in Spain.
A legal review can help you confirm which rules apply, which return must be filed, and whether the treaty between Spain and the UAE affects the final result.
Holding significant assets in Spain
If you hold substantial assets in Spain, Wealth Tax may need to be reviewed alongside your broader cross-border tax position.
Asset value, location, and residence status can all influence the outcome, so this is often one of the areas where careful advice is most useful.
Managing tax exposure in both Spain and the UAE
When Spain and the UAE both connect to your financial life, the treaty between the two countries becomes an important reference point.
It helps allocate taxing rights and reduce double taxation, and this is often where we can guide you with the most clarity at Diaz & Asociados, especially when the facts cross more than one jurisdiction.
Frequently Asked Questions About Spanish Tax Laws
Do I need a Spanish tax identification number before filing a tax return?
Yes. To file with the Spanish Tax Agency, you generally need a Spanish tax identification number, and depending on your situation this may be linked to your NIE or another identification format accepted by the authorities.
Can regional tax rules change the amount of tax I pay in Spain?
Yes. Spain has state taxes, but some parts of the tax system are partly ceded to the autonomous communities, which can affect the final result in areas such as Personal Income Tax, Wealth Tax, and Inheritance and Gift Tax.
What happens if I file a Spanish tax return late?
A late filing can lead to surcharges, interest, or penalties under the General Tax Law, and the exact result depends on the type of return, the timing, and whether the filing is voluntary or follows action by the tax authorities.
Can I correct a Spanish tax return after submitting it?
Yes. The Spanish Tax Agency allows taxpayers to correct or amend a return in certain cases, including situations where the original filing caused harm to the taxpayer or where information needs to be updated.
What documents should I keep to support my tax position between Spain and the UAE?
It is sensible to keep travel records, proof of residence, income documents, property records, and any tax residence certificate relevant to your case, especially where the Spain and UAE treaty may affect the way your income is taxed.